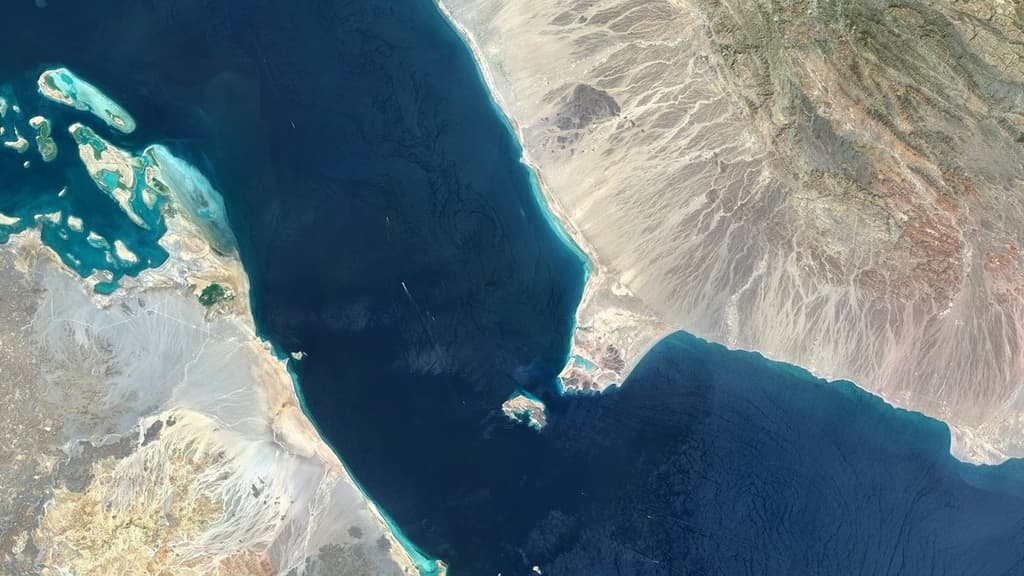
**Ongoing Houthi control over key Yemeni coastal positions near the Bab el-Mandeb Strait, combined with selective targeting of Saudi-linked shipping and persistent war-risk premiums, continues to suppress weekly transits into the low-to-mid 20s per day range.** Recent seizures of Mokha port, Hanish Islands, and Perim Island in early-to-mid September have heightened operational risks without triggering a full closure, leading many carriers to maintain partial rerouting via the Cape of Good Hope or sail with AIS transponders dark. This has stabilized volumes after sharp July drops but kept them well below pre-2023 baselines of roughly 35–60+ vessels daily across segments. Data through late September show weekly aggregates clustering around 170–210 total transits (roughly 24–30 per day), with tanker traffic hit hardest (often 6–8 per day) while cargo shows modest resilience. Some major liners have restored limited Suez services, supporting the competitive 170–189 and 190–209 bins, yet elevated insurance costs, potential last-minute diversions, and satellite-only tracking gaps create meaningful variance. The closely matched leading probabilities reflect trader focus on real-time AIS and satellite feeds versus the risk of sudden escalation or further dark-ship increases ahead of week-end resolution.
Experimental AI-generated summary referencing Polymarket data. This is not trading advice and plays no role in how this market resolves. · UpdatedView resolved
Beware of external links.
Beware of external links.
Frequently Asked Questions