
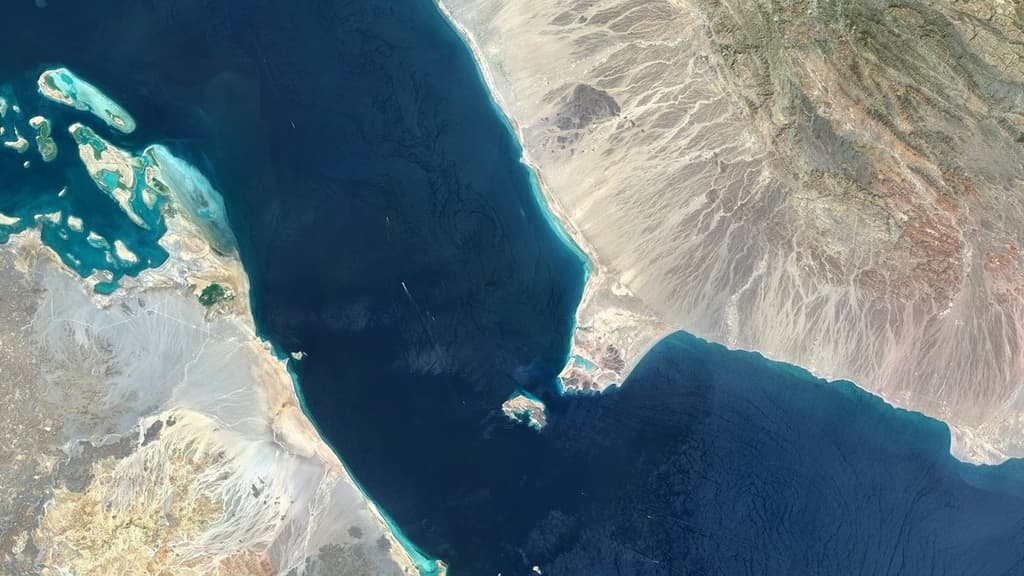
Persistent Houthi threats, including the July 2026 Saudi shipping blockade and subsequent attacks on tankers, combined with intensified Gulf conflict disrupting Strait of Hormuz flows, remain the dominant factors suppressing Bab el-Mandeb transits. Recent AIS and tracking data show daily crossings hovering in the low-to-mid 20s (e.g., 21–24 vessels mid-September), with tanker volumes especially depressed at 3–8 per day, well below pre-crisis baselines near 60 daily. This trajectory positions the <170 weekly bin at 39% implied probability as the market consensus, followed by the 170–189 range, reflecting trader expectations of sustained rerouting and risk aversion into the week of September 14. Elevated war-risk premiums and selective targeting continue to limit recovery, with no near-term catalysts evident to shift volumes materially higher before resolution.
Tóm tắt AI thử nghiệm tham chiếu dữ liệu Polymarket. Đây không phải tư vấn giao dịch và không ảnh hưởng đến cách thị trường này được giải quyết. · Cập nhậtHow many ships transit Bab el-Mandeb Strait week of September 14?
How many ships transit Bab el-Mandeb Strait week of September 14?
<170 39%
170-189 24%
190-209 22%
210-229 9%
<170
39%
170-189
24%
190-209
22%
210-229
9%
230+
3%
<170 39%
170-189 24%
190-209 22%
210-229 9%
<170
39%
170-189
24%
190-209
22%
210-229
9%
230+
3%
Transit calls include container, dry bulk, roll-on/roll-off, general cargo, and tanker ships. Ships not reported by IMF Portwatch will not be considered.
This market will resolve as soon as all relevant data has been published. If the relevant data is not published within 14 calendar days of the specified date, this market will resolve based on the most recent data published up to that point.
In case of obvious data integrity issues (i.e., erroneous data), the market may remain open until the end of the third calendar day (ET) after the date on which such data is first released to allow for corrections. Data integrity issues refer only to clerical or other similar errors in the underlying data, and do not include cases where IMF Portwatch differs from alternative sources.
Only revisions to previously published data points made before all relevant data has been published will be considered.
The resolution source for this market will be IMF PortWatch, specifically the “Arrivals of Ships” data published for the Bab el-Mandeb Strait at https://portwatch.imf.org/pages/6b1814d64903461b98144a6cc25eb79c.
Thị trường mở: Sep 11, 2026, 5:48 PM ET
Nguồn giải quyết
https://portwatch.imf.org/pages/6b1814d64903461b98144a6cc25eb79cNgười giải quyết
0x69c47De9D...Transit calls include container, dry bulk, roll-on/roll-off, general cargo, and tanker ships. Ships not reported by IMF Portwatch will not be considered.
This market will resolve as soon as all relevant data has been published. If the relevant data is not published within 14 calendar days of the specified date, this market will resolve based on the most recent data published up to that point.
In case of obvious data integrity issues (i.e., erroneous data), the market may remain open until the end of the third calendar day (ET) after the date on which such data is first released to allow for corrections. Data integrity issues refer only to clerical or other similar errors in the underlying data, and do not include cases where IMF Portwatch differs from alternative sources.
Only revisions to previously published data points made before all relevant data has been published will be considered.
The resolution source for this market will be IMF PortWatch, specifically the “Arrivals of Ships” data published for the Bab el-Mandeb Strait at https://portwatch.imf.org/pages/6b1814d64903461b98144a6cc25eb79c.
Nguồn giải quyết
https://portwatch.imf.org/pages/6b1814d64903461b98144a6cc25eb79cNgười giải quyết
0x69c47De9D...Persistent Houthi threats, including the July 2026 Saudi shipping blockade and subsequent attacks on tankers, combined with intensified Gulf conflict disrupting Strait of Hormuz flows, remain the dominant factors suppressing Bab el-Mandeb transits. Recent AIS and tracking data show daily crossings hovering in the low-to-mid 20s (e.g., 21–24 vessels mid-September), with tanker volumes especially depressed at 3–8 per day, well below pre-crisis baselines near 60 daily. This trajectory positions the <170 weekly bin at 39% implied probability as the market consensus, followed by the 170–189 range, reflecting trader expectations of sustained rerouting and risk aversion into the week of September 14. Elevated war-risk premiums and selective targeting continue to limit recovery, with no near-term catalysts evident to shift volumes materially higher before resolution.
Tóm tắt AI thử nghiệm tham chiếu dữ liệu Polymarket. Đây không phải tư vấn giao dịch và không ảnh hưởng đến cách thị trường này được giải quyết. · Cập nhật
Cẩn thận với liên kết bên ngoài.
Cẩn thận với liên kết bên ngoài.
Câu hỏi thường gặp