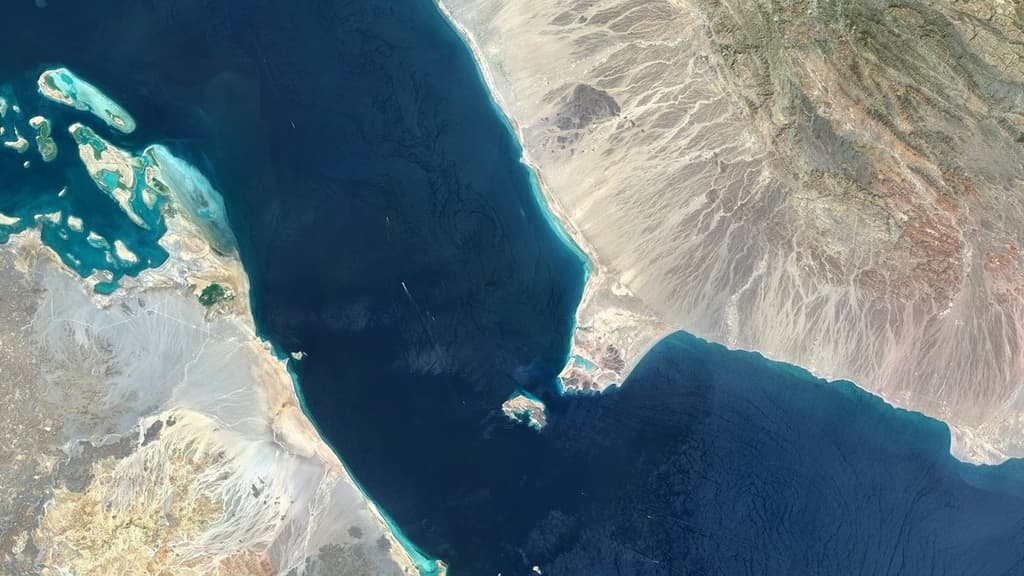
Recent Houthi territorial advances, including the early-September seizure of Perim Island and Mokha port, have intensified risks at the Bab el-Mandeb chokepoint, prompting rerouting, higher war-risk premiums, and a maritime embargo targeting Saudi-linked vessels. This has compressed daily transits to roughly 20–30 vessels in mid-September, down sharply from 2023 baselines near 60 per day and consistent with Kpler and AIS data showing 21 crossings on September 14 versus 28 the prior day. Trader consensus clusters around 170–209 weekly totals, reflecting uncertainty over whether attacks will sustain the current suppression or allow modest recovery ahead of resolution. Oil price spikes near $110 per barrel underscore the broader supply-chain impact, while upcoming data on compliance with the embargo and any de-escalation signals represent key swing factors for the range.
Experimental AI-generated summary referencing Polymarket data. This is not trading advice and plays no role in how this market resolves. · UpdatedHow many ships transit Bab el-Mandeb Strait week of September 14?
How many ships transit Bab el-Mandeb Strait week of September 14?
<170 31%
170-189 28%
190-209 24%
210-229 13%
<170
31%
170-189
28%
190-209
24%
210-229
13%
230+
8%
<170 31%
170-189 28%
190-209 24%
210-229 13%
<170
31%
170-189
28%
190-209
24%
210-229
13%
230+
8%
Transit calls include container, dry bulk, roll-on/roll-off, general cargo, and tanker ships. Ships not reported by IMF Portwatch will not be considered.
This market will resolve as soon as all relevant data has been published. If the relevant data is not published within 14 calendar days of the specified date, this market will resolve based on the most recent data published up to that point.
In case of obvious data integrity issues (i.e., erroneous data), the market may remain open until the end of the third calendar day (ET) after the date on which such data is first released to allow for corrections. Data integrity issues refer only to clerical or other similar errors in the underlying data, and do not include cases where IMF Portwatch differs from alternative sources.
Only revisions to previously published data points made before all relevant data has been published will be considered.
The resolution source for this market will be IMF PortWatch, specifically the “Arrivals of Ships” data published for the Bab el-Mandeb Strait at https://portwatch.imf.org/pages/6b1814d64903461b98144a6cc25eb79c.
Market Opened: Sep 11, 2026, 5:48 PM ET
Resolution Source
https://portwatch.imf.org/pages/6b1814d64903461b98144a6cc25eb79cResolver
0x69c47De9D...Transit calls include container, dry bulk, roll-on/roll-off, general cargo, and tanker ships. Ships not reported by IMF Portwatch will not be considered.
This market will resolve as soon as all relevant data has been published. If the relevant data is not published within 14 calendar days of the specified date, this market will resolve based on the most recent data published up to that point.
In case of obvious data integrity issues (i.e., erroneous data), the market may remain open until the end of the third calendar day (ET) after the date on which such data is first released to allow for corrections. Data integrity issues refer only to clerical or other similar errors in the underlying data, and do not include cases where IMF Portwatch differs from alternative sources.
Only revisions to previously published data points made before all relevant data has been published will be considered.
The resolution source for this market will be IMF PortWatch, specifically the “Arrivals of Ships” data published for the Bab el-Mandeb Strait at https://portwatch.imf.org/pages/6b1814d64903461b98144a6cc25eb79c.
Resolution Source
https://portwatch.imf.org/pages/6b1814d64903461b98144a6cc25eb79cResolver
0x69c47De9D...Recent Houthi territorial advances, including the early-September seizure of Perim Island and Mokha port, have intensified risks at the Bab el-Mandeb chokepoint, prompting rerouting, higher war-risk premiums, and a maritime embargo targeting Saudi-linked vessels. This has compressed daily transits to roughly 20–30 vessels in mid-September, down sharply from 2023 baselines near 60 per day and consistent with Kpler and AIS data showing 21 crossings on September 14 versus 28 the prior day. Trader consensus clusters around 170–209 weekly totals, reflecting uncertainty over whether attacks will sustain the current suppression or allow modest recovery ahead of resolution. Oil price spikes near $110 per barrel underscore the broader supply-chain impact, while upcoming data on compliance with the embargo and any de-escalation signals represent key swing factors for the range.
Experimental AI-generated summary referencing Polymarket data. This is not trading advice and plays no role in how this market resolves. · Updated
Beware of external links.
Beware of external links.
Frequently Asked Questions